By Hamza Faisal
The AI boom has a bottleneck, and it is not chips. It is electricity. The world's largest tech companies can design bigger models and buy more servers, but they cannot run them without power, grid connections, and cooling — and in the places where data centres are concentrating, those three things are running out first. Here is how the power problem works, in numbers, and why it decides the pace of AI itself.
The scale of the surge
Start with the global picture. According to the International Energy Agency, global data centre electricity use is on pace to roughly double from about 485 terawatt-hours in 2025 to 950 terawatt-hours by 2030 — nearly 3 percent of all electricity demand on Earth. AI-focused facilities are growing even faster: their consumption is on track to triple over the same period after surging 50 percent in 2025 alone. The United States and China together account for close to 80 percent of the increase.
Gartner's snapshot of 2026 tells the same story in capacity terms: global data centre power demand is projected to reach 132 gigawatts in 2026, up from 104 gigawatts in 2025, and climb to roughly 290 gigawatts by 2030. AI-optimised servers alone are projected to use 175 terawatt-hours in 2026, nearly double their 2025 consumption — and by 2027, they are expected to overtake conventional servers entirely. This is not a gradual trend. It is a step change in what computing consumes.
Why the grid cannot just keep up
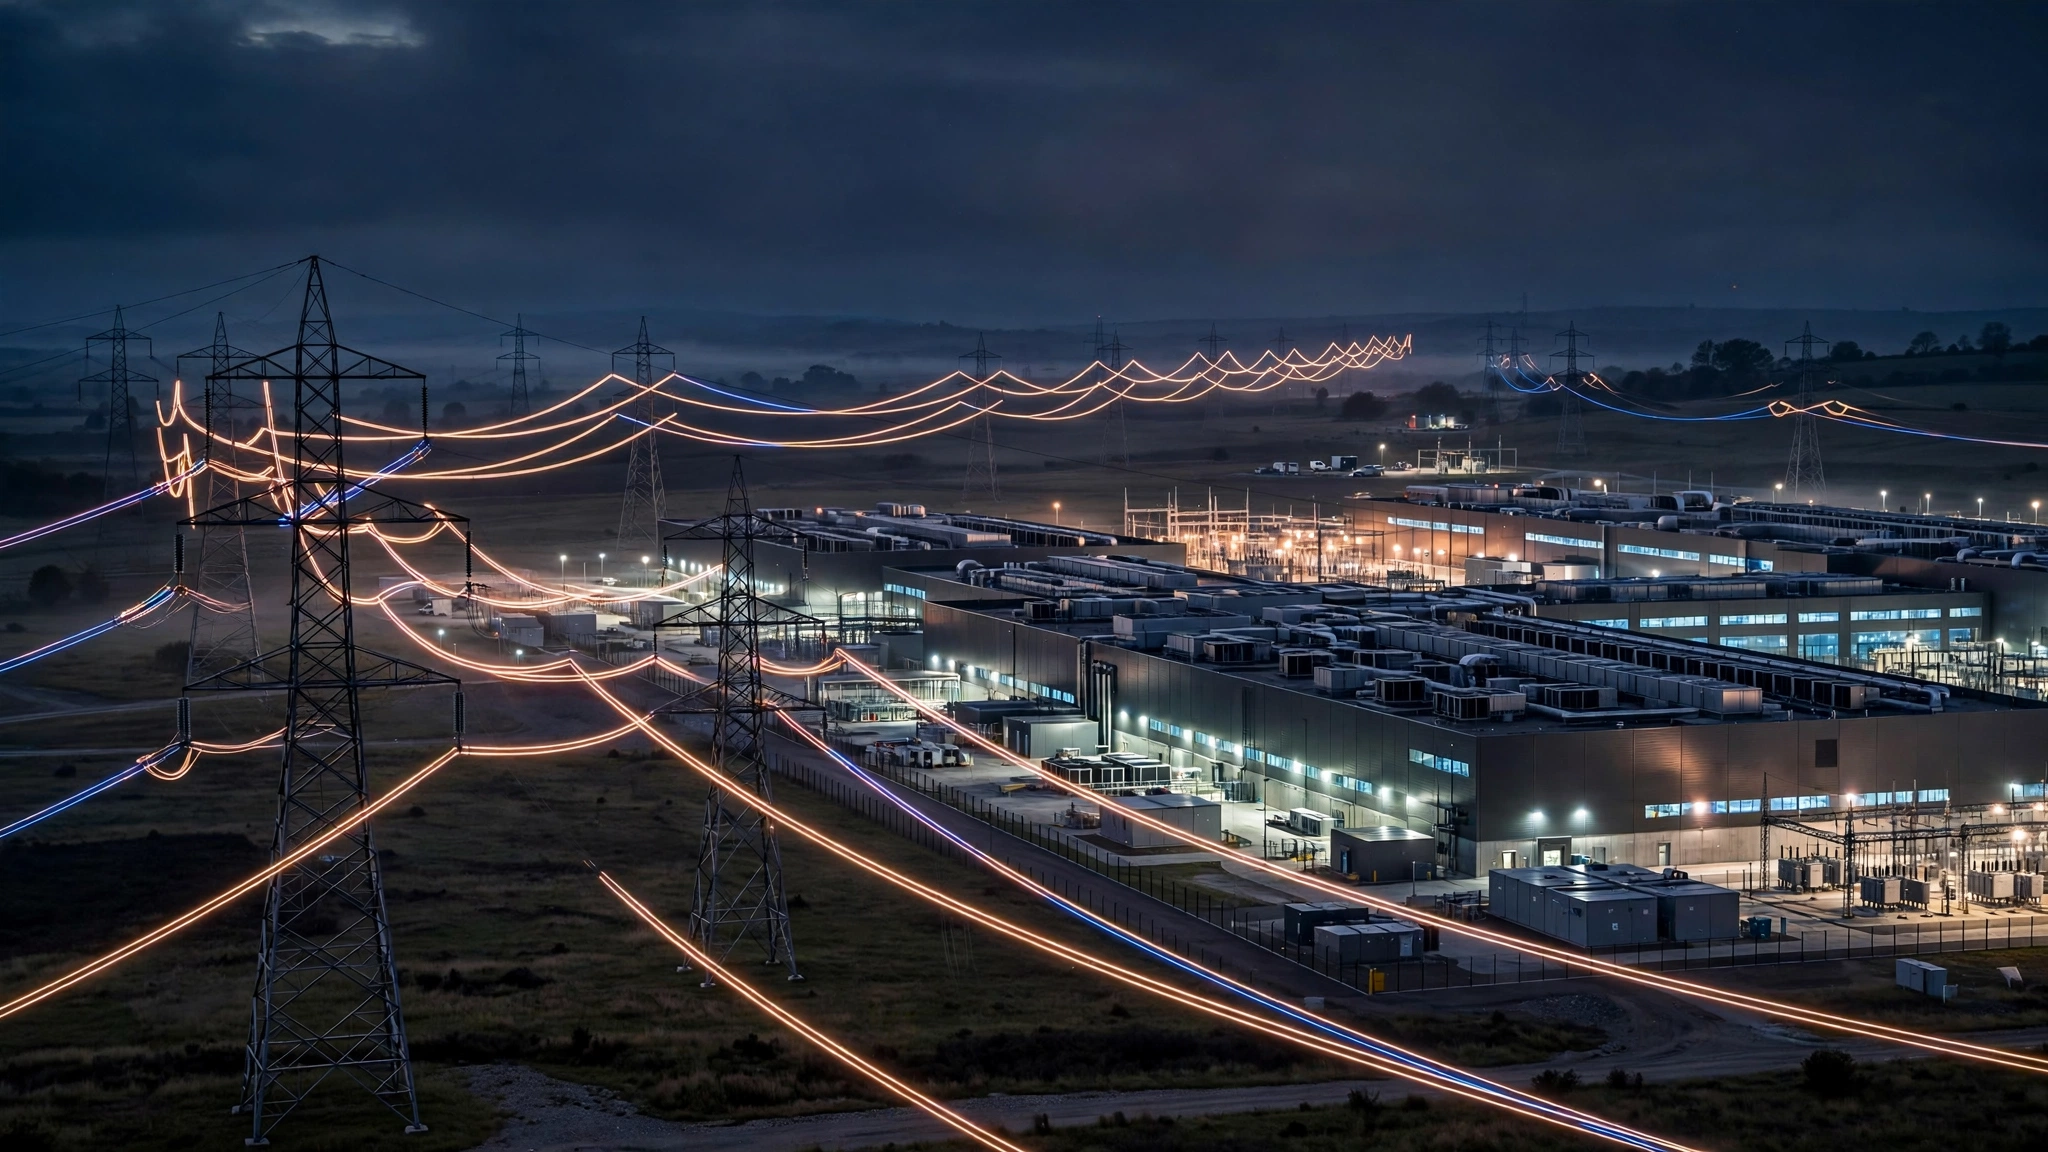
The core problem is speed and location. Building power plants, substations and transmission lines takes years; hyperscale AI campuses are proposed and built on much shorter timelines. Individual AI sites now request 100 to 750 megawatts each — the equivalent of a small city — and nearly 2,300 gigawatts of generation and storage capacity is sitting in US interconnection queues, more than the country's entire installed power base, with waits stretching past five years in many regions.
The pressure is concentrated, not evenly spread. PJM, the grid serving 67 million people across 13 US states, expects roughly 30 to 32 gigawatts of new peak demand by 2030, with data centres responsible for about 94 percent of that growth. Texas's ERCOT is weighing more than 474 gigawatts of large-load requests, about 90 percent from data centres — more than five times the grid's record peak. Ireland shows what saturation looks like at national scale: data centres consumed 22 percent of the country's metered electricity in 2024. Gartner projects that 40 percent of AI data centres will be power-constrained by 2027.
Who pays for it
Grid upgrades are expensive, and the bill lands somewhere. Utilities requested tens of billions of dollars in rate increases to fund upgrades, and some residential customers near major data centre hubs have already seen bills rise sharply in a single year. Virginia, home to the densest concentration of data centres in the world, introduced a consumption tax of $0.011 per kilowatt-hour on data centre electricity from July 1, 2026, expected to raise around $600 million a year. Lawmakers elsewhere have introduced legislation aiming to shift upgrade costs away from ordinary ratepayers — the politics of who funds the AI buildout is now a live fight.
The industry's response is to go around the grid. Microsoft and Chevron signed a 20-year agreement for dedicated on-site generation for a planned data centre campus near Pecos, Texas — one of the largest direct pairings of compute and power generation yet. Expect more of this: when the grid queue is five years long, building your own power starts to look fast. Meanwhile, the US Department of Energy's $967 million grid funding announced in October 2026 is narrower than the headlines suggested — it flows through a resilience program built for storms and wildfires, not for connecting AI load.
What could break first
When engineers talk about grid risk, they rarely mean the total amount of electricity a country produces. They mean specific pieces of equipment in specific places. Transformers are a leading example: large power transformers are custom-built, take months or years to manufacture, and the world already faces shortages. Substations, transmission corridors and interconnection approvals are the other choke points. A data centre can be built in 18 months; the substation feeding it can take far longer. That mismatch is why so much capacity sits in queues, and why "we have enough power nationally" is the wrong reassurance for a region where a dozen campuses are competing for the same substations.
Cooling is the second constraint hiding behind the power numbers. AI servers run hot, and the infrastructure that cools them — water, chillers, air handling — consumes a growing share of a facility's electricity. Gartner estimates cooling and other infrastructure will consume 195 terawatt-hours globally in 2026, up from 159 terawatt-hours in 2025. In water-stressed regions, that creates a second negotiation: not just megawatts, but litres. Expect future data centre fights to be about water permits as much as power permits.
The efficiency counter-argument — and its limits
There is a genuine counter-argument, and it deserves a fair hearing. Newer hardware does more work per watt than older hardware, and the industry's shift to renewables is real: renewables supply about 27 percent of global data centre electricity, with total renewable generation projected to grow around 22 percent annually through 2030, covering nearly half of anticipated demand growth. More efficient chips, better cooling, and smarter workload scheduling all blunt the surge.
But efficiency has a rebound problem. When computing gets cheaper per unit, people use more of it — more queries, bigger models, more features — and total consumption keeps rising anyway. That is exactly what the data shows: AI-optimised server consumption nearly doubling in a single year, even as each server gets more efficient. Efficiency slows the growth; it does not stop it. The grid still has to deliver the total, and the total is still climbing roughly 15 percent per year — more than four times faster than electricity demand from every other sector combined.
What this means for AI's future
Power is now the gating factor on AI progress. Model capability can keep improving in the lab, but deploying it at scale depends on deliverable megawatts, substations and interconnection approvals. That is why the most important AI stories of the next few years may be about transformers, transmission corridors and utility regulators rather than model releases. The companies that secure firm power — through grid deals, on-site generation, or sites near abundant energy — will set the pace. Everyone else waits in the queue.
Sources: Gigenet, AI Data Center Power Crisis; EBC, AI Data Centers: 2026 Power Demand Shock; AI Vibe, AI Data Centers Are Eating the Power Grid; International Energy Agency and Gartner projections as reported therein.